[Tier-1 stub] Securities issuance results report
2026-09-14 17:47 KST: NH투자증권 (005940, KOSPI) appeared on DART todayRSS — 「증권발행실적보고서」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
last refresh 2026-09-14 21:54 HKT / 2026-09-14 22:54 KST
Research/paper only. KR PREOPEN (cash 09:00 KST). HK 09:30 HKT. US overnight — Mon RTH 21:30 HKT. Fri closes ≠ Mon gap. NXT is indication only, not cash. Do not treat Yahoo prev-close as a Monday gap.
watchlists Korea attractive EMPTY besides Hynix desk. Weekend leftover DART: KEEP Korea Advanced Materials 062970 Lucent LP add ₩14.7bn (mixed/3-8%/p≈30% into Mon open). AJ: ORCL NEW vs Y (beat/raise + Post Q3 memo; entry HC-gated — still wait, not a confirmed public long). AMD Y confirmation (+14%/9d). Standing Y: AVGO / MU / MRVL / NVDA / XPEV / META / AMD. NIO/TSLA caution; EOS/EOSE avoid.
news Fri KOSPI 6,909.91 (−1.76%) vs Thu 7,033.92. Hynix ₩1,812,000 (−2.21%); Samsung ₩259,500 (−3.53%). For −₩2.29tn / Inst −₩1.22tn / Ind +₩1.87tn (Yonhap). NXT now: 000660 ₩1,755,000 (−3.15%); 005930 ₩254,000 (−2.12%). HSI Fri 24,805.63 (−0.60%). Zhipu 793 (−3.2%); MiniMax 270 (−7.5%); SenseTime 1.31 (+0.4%). Weekend: DeepSeek V4.1 Flash HBM scare; SCMP Z.ai ~US$5b raise; Anthropic Claude distillation claims; US CPI +0.4%/3.4% (core +0.3%) → ~90% Fed hike odds mid-week.
X Evening refresh (US hours): 4 NEW since 14:09 — @jukan05 TrendForce 4-Hi isn’t enough + SEMCO–QCOM organic bridge + TeraFab WFE orders (ASML/AMAT/LRCX/TEL; Hanmi packaging); @zephyr_z9 China AI labs ~$35B since Jun (path ~$60B by Jan’27). AJ no new ticker (AMD confirm / ORCL memo still prior). Sentiment still mixed (medium). Home unavailable.
HYROX Warsaw still Ticket sales start soon! Official page unchanged (7–11 Apr 2027). Outlook not re-scanned this pass (browser MCP unavailable); prior 13 Sep evening: no registration-open mail. No ping.
DART NEW KEEP CK Solution 480370 SK Hynix Indiana FAB MPH PKG#4 (CUB) ₩147.68bn via US sub (~213% mcap / ~51% sales; up/8%+/p≈10%; live already +19.8%/high +27.7%). Prior today: Woori Ro 046970; Now IB 293580; Sebo MEC 011560; CK StarPlus ESS; VC buyback; Toolgen rights; Innotena CB; SHI LNG; weekend KAM 062970. Dropped Dabolink ₩0.47bn small offering wrap. 2026-09-14 14:58 KST
funding BN↔HL mark: SKHX ~+1.0 bp (BN 1303.23 / HL 1303.1), SKHY ~+1.6 bp (BN 181.89 / HL 181.86). BN lastFR SKHYNIX +3.02 bp / SKHY 0. HL hourly SKHX +0.36 bp / SKHY +2.22 bp. Next BN funding 08:00 HKT. Est. 8h long-BN/short-HL SKHX ~−0.1 bp / SKHY ~+17.8 bp (HL hourly×8 path risk; SKHY HL funding noisy). Marks tight vs Thu gap. Paper.
Hynix Fri cash ₩1,812,000 (−2.21%); For −606.5k / Inst −274.5k / Ind +277.1k (Naver). NXT ₩1,755,000 (−3.15%). ADR Fri $190.07 (+0.94% vs Thu $188.30) / parity ~₩1.812m÷10 @ Yonhap 1345.9 → prem ~+41.2%. KIND/DART: no new 000660. Best paper: 09:00 auction vs soft NXT after Fri DeepSeek/foreign dump — not BN↔HL (~1 bp). Paper only.
impact Soft Mon setup: Fri oil+DeepSeek+foreign dump printed; NXT −3% into auction; Z.ai dilution filing overnight; hot CPI into FOMC; ADR still rich vs soft KRX. Watch 09:00 vs NXT, 062970 leftover, HK AI open 09:30 (Z.ai raise), FOMC week. No live.
Mon age window · Fri 15:40 KST → now · stubs banned · scan 2026-09-14 15:01 HKT / 2026-09-14 16:01 KST · 12 keep(s) · KEEP Hanshin 004960 + STX 011810 · purged stubs
2026-09-14 17:47 KST: NH투자증권 (005940, KOSPI) appeared on DART todayRSS — 「증권발행실적보고서」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 17:52 KST: NH투자증권 (005940, KOSPI) appeared on DART todayRSS — 「증권발행실적보고서」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 17:36 KST: GS (078930, KOSPI) appeared on DART todayRSS — 「[기재정정]장래사업ㆍ경영계획(공정공시)」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 17:43 KST: NH투자증권 (005940, KOSPI) appeared on DART todayRSS — 「증권발행실적보고서」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 17:16 KST: 한화투자증권 (003530, KOSPI) appeared on DART todayRSS — 「일괄신고추가서류(기타파생결합사채)」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 17:22 KST: 한화투자증권 (003530, KOSPI) appeared on DART todayRSS — 「투자설명서(일괄신고)」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 17:24 KST: NH투자증권 (005940, KOSPI) appeared on DART todayRSS — 「[발행조건확정]증권신고서(채무증권)」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 17:29 KST: NH투자증권 (005940, KOSPI) appeared on DART todayRSS — 「증권발행실적보고서」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 17:00 KST: GS (078930, KOSPI) appeared on DART todayRSS — 「특수관계인에대한출자」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 17:10 KST: LG (003550, KOSPI) appeared on DART todayRSS — 「최대주주등소유주식변동신고서」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 16:50 KST: 신한지주 (055550, KOSPI) appeared on DART todayRSS — 「증권발행실적보고서」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 16:54 KST: 대우건설 (047040, KOSPI) appeared on DART todayRSS — 「타인에대한채무보증결정」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 16:57 KST: 효성중공업 (298040, KOSPI) appeared on DART todayRSS — 「[기재정정]단일판매ㆍ공급계약체결」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 16:35 KST: 고영 (098460, KOSDAQ) appeared on DART todayRSS — 「기업설명회(IR)개최」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 16:39 KST: 포스코인터내셔널 (047050, KOSPI) appeared on DART todayRSS — 「금전대여결정」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 16:41 KST: 이수스페셜티케미컬 (457190, KOSPI) appeared on DART todayRSS — 「기업설명회(IR)개최(안내공시)」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 16:44 KST: 포스코인터내셔널 (047050, KOSPI) appeared on DART todayRSS — 「기업설명회(IR)개최(안내공시)」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 16:01 KST: 포스코인터내셔널 (047050, KOSPI) appeared on DART todayRSS — 「타인에대한채무보증결정」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 16:03 KST: HD한국조선해양 (009540, KOSPI) appeared on DART todayRSS — 「영업(잠정)실적(공정공시) (자회사의 주요경영사항)」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 16:04 KST: HD한국조선해양 (009540, KOSPI) appeared on DART todayRSS — 「영업(잠정)실적(공정공시)」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 16:04 KST: 삼성증권 (016360, KOSPI) appeared on DART todayRSS — 「증권발행실적보고서」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 16:05 KST: KB금융 (105560, KOSPI) appeared on DART todayRSS — 「증권발행실적보고서」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 16:07 KST: HD현대중공업 (329180, KOSPI) appeared on DART todayRSS — 「영업(잠정)실적(공정공시)」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 16:08 KST: 보로노이 (310210, KOSDAQ) appeared on DART todayRSS — 「[기재정정]투자판단관련주요경영사항(임상시험계획변경승인) (VRN110755의 제 1/2상 임상시험)」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
2026-09-14 16:12 KST: 포스코인터내셔널 (047050, KOSPI) appeared on DART todayRSS — 「타법인주식및출자증권취득결정」. Stub only from RSS title; body not fetched. Direction unclear/mixed until enrich.
What: process extension only — committee vote on whether to delist is delayed for more diligence on the rehab plan, not a rescue or a delisting confirmation. Why mixed: more time can briefly lift 'not dead yet' hopes on a management/halted name, but the July finding that delisting criteria were met still stands and overhang remains. Why 3-8%: when/if single-price or trading resumes around the eventual committee outcome, these names usually gap mid-to-high single digits either way; extension itself is not an 8%+ cash event. Why p≈20%: name is halted today (tradableStatus halt), so next regular cash session may not print at all until KRX lifts the halt — leftover is contingent on a session existing.
What: contractor selection (시공자 선정), not a signed EPC yet — face ₩228.3bn is ~19.9% of sales and ~167% of ~₩136bn mcap, but cash will drip over a multi-year housing rebuild with no advance disclosed. Why up: being named builder is incremental backlog for a cheap construction name (PBR ~0.16). Why only 1-3%: unsigned + progress-bill construction class (Samsung E&A / Seohan-style) — face/mcap looks 8%+ but near-term cash does not; expect a headline blip not a melt-up. Why p≈35%: after-close stamp into Tue open is a real leftover window on a thin tape (~14k shares today), but selection news often leaks and the band is small.
What: mid-session voluntary stamp that U.S. sub CK AMERICA signed an SK Hynix Indiana FAB MPH PKG#4 (CUB) infra contract for ₩147.68bn (~50.8% of FY25 sales / ~213% of ~₩69bn mcap), U.S. delivery window through end-Oct 2028; contract dated/received 11 Sep, filed 14 Sep 14:41. Why up: named SK Hynix AI-memory advanced-packaging fab backlog is visible order intake for a thin DR/CR/special-equipment KOSPI name — positive utilization/revenue path, not dilution or liability; Hynix Indiana narrative is a real demand signal. Why 8%+ not 1-3%/3-8%: face clears well past an 8%+ mcap bar on a ~₩69bn name and thin tape already whipped (live +19.8% / high +27.7%); Hynix FAB AI-packaging naming on a micro-mcap can print auction-shock class even when cash is progress-bill. Caveat inside the band: Samsung E&A / progress-bill rule still applies — no advance disclosed, amount/period may change with construction progress, and cash drips through Oct 2028 — so near-term cash does NOT justify holding the full gap; expect Sammok/Dual-style spike-and-fade rather than a durable re-rating. Sales% (~51%) is disclosure materiality, not the price band. Why p≈10%: live already +19.8% / high +27.7% into enrich, so an 8%+-class spike has already printed and is partially giving back from the high; leftover vs a further 8%+ from live is thin. Mid-session enrich plus three-day stamp lag (order 11 Sep → file 14 Sep) and the earlier StarPlus ESS stamp on the same sub mean first clip is likely done. Desk Why around the DART timestamp; paper until Risk signs.
Why up: named third-party U.S./photonic data-center backlog is real order intake on a KOSDAQ name. Why only 1-3%: sales% is disclosure materiality not the price band; face is ~4% of mcap with no advance and cash dripping through mid-2028 (Vinatech/progress-bill class). Live ~₩7,285 (+1.3% vs ₩7,190 / high ₩7,950 = +10.6%) into enrich — first clip already printed and faded; leftover is residual grind not a clean unused open. Dropped companion noise; not SK Hynix.
What: mid-session board decision on a 4:1 reverse stock split that cuts share count and capital stock by 75% (94.93m → 23.73m shares; capital ₩47.89bn → ₩12.29bn), with a planned multi-week trading halt 20 Nov–17 Dec around the 23 Nov record date; stamped 14 Sep 13:42 with a matching KRX halt notice. Why mixed: mechanically this is a free consolidation — equity value per holder is unchanged aside from odd-lot cash — so it is not dilution, not a cash buyback, and not a cash capital reduction. Soft positive: management frames shareholder-return capacity and capital clean-up. Soft negative: “KOSDAQ listing maintenance” language plus a ~4-week halt is a listing-compliance / friction signal that often trades poorly near-term on thin KOSDAQ. Why 1-3% not 3-8%/8%+: no cash leaves or enters the firm (₩35.60bn lands in capital surplus only); size of the cut is optical/share-count, not a same-day cash event. Thin ADV (~₩0.11bn session) can still whip a headline, but the economic band for a pure reverse-split + future-halt stamp is small. Why p≈28%: live still near unchanged (−0.36%) so leftover into a 1-3% band is not zero; but mid-session enrich ~4 min after the 13:42 stamp means the first clip window is already open — leftover is a residual grind into the close / next session, not an auction gap. Haircut for value-neutral mechanics and listing-maintenance stigma. Desk Why around the DART timestamp; paper until Risk signs.
What: mid-session Samsung C&T Pyeongtaek piping works #3 award for ₩105.73bn (~14.8% of FY25 sales / ~43.6% of ~₩243bn mcap), advance present, delivery through end-Sep 2027; stamped 14 Sep 13:19. Why up: named third-party Samsung C&T backlog with an advance is visible near-term order intake for a KOSDAQ MEP/piping name — positive utilization/revenue path, not dilution or liability. Why 3-8% not 1-3%/8%+: face clears an 8%+ mcap bar on a ~₩243bn name and thin ADV (~₩1.9bn session) can whip; but Samsung E&A / construction progress-bill rule applies — advance size is undisclosed, cash drips over ~1 year to Sep 2027, and the form flags prior similar Samsung C&T work (동종계약), so this is not a first-time franchise surprise or automatic same-day 8%+ fuel. Sales% (~15%) is disclosure materiality, not the price band. Mid-session clock also cuts an auction-gap thesis. Why p≈28%: live still flat (0.00%) so leftover into a 3-8% band is not zero; but high already +5.61% then faded to flat means the first clip partially printed and gave back — leftover is for a re-grind from flat, not a clean unused open. Enrich ~8 min after the 13:19 stamp. Haircut for mid-session timing and known-CP continuity. Desk Why around the DART timestamp; paper until Risk signs.
What: mid-session voluntary stamp that U.S. sub CK AMERICA signed a StarPlus Energy LLC SPE LFP ESS 365Ah supply contract for ₩57.14bn (~19.6% of FY25 sales / ~94% of ~₩61bn mcap), U.S. delivery window through end-2027; contract dated 11 Sep, filed 14 Sep 11:33. Why up: named third-party U.S. ESS backlog with StarPlus Energy is visible order intake for a thin DR/CR/special-equipment KOSPI name — positive utilization/revenue path, not dilution or liability. Why 3-8% not 1-3%/8%+: face clears an 8%+ mcap bar on a ~₩61bn name and thin tape can whip, but Samsung E&A / progress-bill rule applies — no advance disclosed, amount/period may change with construction progress, and cash drips through 2027, so near-term cash is not automatic same-day 8%+ fuel. Sales% (~20%) is disclosure materiality, not the price band. Why p≈18%: live already +4.55% / high +14.8% into enrich, so an 8%+-class spike has already printed and partially faded; leftover vs a further 3-8% from live is thin. Mid-session enrich plus three-day stamp lag (order 11 Sep → file 14 Sep) means first clip is likely done. Desk Why around the DART timestamp; paper until Risk signs.
What: mid-session paired cancel-bound buyback trust + treasury cancel for ₩1.0bn (~5.3–5.5% of ~₩18–19bn mcap / ~5.5% of float at the ₩2,500 sizing price), open-market via Yuanta over up to one year, with an explicit commitment to cancel all acquired shares after the buy completes. Why up: cash bid into the order book plus a float-shrink cancel path is classic Sammok/Dual/Innotena-class price-support + scarcity — not ESOP (shares return to float) and not a hold-only support bid. Why 3-8% not 1-3%/8%+: face clears a mid-single mcap bar on a thin ~₩19bn KOSDAQ name, and cancel language can whip hard; but this is NOT PlumbFast already-held immediate cancel — acquisition runs as late as Sep 2027 and cancel date is blank, so today is a new cash-bid headline, not an instant permanent float cut. Mid-session (not auction) also cuts an automatic 8%+ gap thesis. Why p≈28%: live already +3.60% / high +6.0% into enrich, so roughly the lower half of a 3-8% band is on the tape; leftover is for a further thin-name grind, not a clean unused open. Enriched Why is minutes after the 11:24 stamp — first clip may already be printed. Haircut for year-long buy window and mid-session clock. Desk Why around the DART timestamp; paper until Risk signs.
What: mid-session lock-in of the already-announced Toolgen rights final issue price at ₩25,050 for 777k new shares (~8.6% of float / ~₩19.5bn / ~7% of ~₩278bn mcap), using the standard 23% discount formula with a 40% max-discount floor; determination dated 11 Sep, stamped to DART 14 Sep 11:11. Why down: this is Keyang/SG-class — final issue price on a known rights deal crystallizes the discount for non-takers; dilution math (~8.6% share count) becomes mechanical, not a fresh capital-raise surprise. Why 1-3% not 3-8%/8%+: share count and structure have been public since the 6 Aug decision / 20 Aug registration / 4 Sep prospectus, so this is a discount lock-in, not a new raise; live already −4.77% (low −6.8% vs prior) into the stamp, so most of a typical same-day reaction is already on the tape — leftover from here is a residual grind, not a fresh 3–8% gap. Why p≈20%: mid-session enriched Why lands after the first clip; leftover vs a further 1–3% from live is modest, and the overnight/auction clock is not open. Haircut for known-deal status and already-printed −5%. Desk Why around the DART timestamp; paper until Risk signs.
What: mid-session ₩5.0bn 2nd-round private 0%/0% CB for R&D working capital (~18% of ~₩28bn mcap), pay-in 22 Sep; conversion into ~13% of shares at ₩7,725 (140% of ref / ~36% above live ₩5,660) only from Sep 2027; put from Sep 2028; issuer/3P call capped at 30%. Why mixed: near-term cash (~18% of mcap) into a thin name is liquidity-positive for R&D runway, but a private CB sold into a pile of KOSDAQ-venture funds is the classic dilution/overhang supply narrative — not a clean buyback or named contract. Strike is OTM with a 1-year conversion lock and no disclosed refixing floor, so this is NOT Codi-class toxic below-spot CB; NBR-class cash-vs-overhang read. Why 3-8% not 1-3%/8%+: face/mcap clears a mid-teens bar and ADV is microscopic (~6,705 shares / ~₩0.4억), so private-CB headlines can whip hard on this tape; but OTM strike + conversion locked to 2027 + constructive cash cut an automatic 8%+ dump or squeeze thesis. Why p≈35%: live only +1.07% so leftover into a 3-8% whip is not zero; stamp 11:00 mid-session with enrich minutes later means the first thin-name clip may still be forming — not an after-close overnight clock. Haircut for mixed mechanism and micro ADV noise. Desk Why around the DART timestamp; paper until Risk signs.
What: mid-session disclosure of a signed Oceania LNG-carrier ×4 yard order worth ₩1,407.8bn (~13% of FY25 sales / ~7.5% of ~₩18.9tn mcap), with advance present but cash otherwise progress-billed through delivery into 2029; contract dated 11 Sep, filed 14 Sep 10:13. Why up: new named-capacity backlog adds visible multi-year yard utilization and revenue recognition path on a core LNG franchise — positive order-intake signal, not a dilution or liability event. Why 1-3% not 3-8%/8%+: face clears a mid-single mcap bar, but Samsung E&A / progress-bill rule applies — multi-year drip + undisclosed advance size means near-term cash is not an 8%+ same-day fuel; liquid ~₩19tn KOSPI ship name usually only pays a ~1% headline blip. Sales% (13%) is disclosure materiality, not the price band. Why p≈25%: live still near unchanged (+0.23%) so leftover vs a 1-3% band is not zero, but mid-session liquid mega-cap + three-day stamp lag (order 11 Sep → file 14 Sep) cut conviction — tape may already have priced whispers, and enriched Why is late vs first clip. Desk Why around the DART timestamp; paper until Risk signs.
What: after-close same-day additional ₩14.7bn cash into own subsidiary Lucent Investment Partnership (~35% of equity / ~25% of ~₩60bn mcap), taking the vehicle to 100% / cumulative ₩21.7bn after a ₩7.0bn print on 4 Sep; purpose is LP capital for unnamed stake buys. Why mixed: face is large enough to matter for HQ liquidity and group capital allocation, but the counterparty is an affiliate/subsidiary fund with no named target and blank financials — consolidated cash may stay in-group while opacity and related-party deployment dominate the tape read (not a clean named M&A or buyback). Why 3-8% not 8%+: face vs mcap clears an 8%+ bar, but affiliate/계열사 rule flags and cuts the band; withheld target + new empty fund is mechanism skepticism, not a free 8%+ open-gap call. Thin ~₩60bn KOSDAQ can still gap hard in NXT/09:00, so 3-8% is the overnight band after the haircut. Why p≈30%: after-close leftover into NXT (15:40–20:00) and Monday/next cash open is a real window; today's +4.5% cash close is prior to the stamp so unused overnight band remains, but mixed/opaque mechanism and same-day name-change noise cut conviction below a clean after-close credit card. Desk Why around the DART timestamp; paper until Risk signs.
2026-09-14 07:42 HKT / 2026-09-14 08:42 KST · Mon morning age-cut Fri after-close → Mon pre-open. 8 items. HKET unavailable. Research only.
Sunday HKEX filing: ~21.97m new H shares at HK$714 (~HK$15.7b / US$2b) plus 20.14bn yuan (~US$3b) CB; stock closed Fri HK$793.
Dilution overhang into Mon open for 2513.HK after Fri’s −3.2% and DeepSeek price war; capital raise signals heavy model/infra burn despite listing premium.
SCMPDeepSeek launched V4.1 Flash (from Sep 10) with sub-cent/million-token pricing and lower KV-cache/HBM needs; MiniMax and Z.AI fell >8% intraday Fri; V4-Pro traffic routes to Flash from Sep 14.
Bearish near-term sentiment for HK AI names and KR memory (HBM intensity narrative); watch Mon NXT already −3% Hynix / −2% Samsung vs Fri.
Business Times (Bloomberg)Sep threat report: ~190M Claude exchanges attributed across seven China-based labs; Moonshot ~23M, DeepSeek ~12.1M, Zhipu >3.4M; SenseTime bought transcripts; MiniMax proxy shell alleged.
Regulatory/reputational risk for named HK/China AI names into the week; may amplify US–China AI export-control politics around NVDA/China and listed peers.
The Hacker NewsFri: foreigners −₩2.29tn, institutions −₩1.22tn, individuals +₩1.87tn; oil/yields and US tech weakness cited; won 1,345.9 at 15:30.
Weak Fri close + Mon NXT gap-down in chips sets risk-off open into FOMC week; foreign selling concentrated in semis.
YonhapSep 1–11: individuals −₩5.21tn Samsung / −₩7.82tn Hynix; foreigners −₩1.96tn each; corporates (treasury) +₩4.66tn / +₩9.89tn.
Ownership transfer to buybacks cushions tape but removes retail bid; foreign still net supply — relevant for Mon follow-through if NXT weakness holds.
Seoul Economic DailyAt Ulsan Forum (remarks Fri, story Sun): AI must monetize to sustain capex; SK–AWS data center ~₩7tn, capacity nearly 900MW.
Soft narrative risk for SK group AI/memory complex if ‘bubble’ talk spreads; medium-term bullish for power/infra demand if build proceeds.
YonhapFri analysis: Samsung risks losing No.2 foundry slot to Chinese peers; analysts point to custom HBM demand as potential stabilizer.
Mixed for 005930: memory HBM still core bull case, foundry competitive pressure rises vs China — reinforces ‘memory > foundry’ framing into the week.
KED GlobalReleased Fri 08:30 ET: gasoline/energy led headline; core hotter than some forecasts; FedWatch hike odds jumped toward ~90%.
Macro headwind for Asia risk assets Mon (higher USD/yields path); supports Fri KR selloff narrative and won/USD sensitivity into FOMC.
BLS000660 / SKHYNIX / xyz:SKHX
KR PREOPEN. Fri cash ₩1,812,000 (−2.21%; For −606.5k / Inst −274.5k / Ind +277.1k — Naver). NXT PRE_MARKET ₩1,755,000 (−3.15%) as of ~07:37 HKT — indication only. Samsung Fri ₩259,500 (−3.53%); NXT ₩254,000 (−2.12%). KOSPI Fri 6,909.91 (−1.76%). KIND/DART: no new clean 000660 keep (last Chongqing rumor reply 20260909800559). data.krx UNKNOWN. Fri overhang: DeepSeek V4.1 Flash HBM scare + foreign dump. BN SKHYNIXUSDT 1303.23 vs HL xyz:SKHX 1303.1 (~+1.0 bp). Paper.
SKHY / xyz:SKHY
SKHY Fri RTH $190.07 (Thu $188.30, +0.94%). FX Yonhap Fri 15:30 1345.9 (Yahoo Mon AM ~1343). ADS=1/10 → parity theo ~$134.63; ADR prem ~+41.2% vs Fri KRW close (richer than Thu ~+37%). BN SKHYUSDT ~181.89 vs HL xyz:SKHY 181.86 (~+1.6 bp). Still structurally rich; Fri ADR green vs KRX red is the cross-venue dissonance. Do not treat NXT −3.15% as an ADR-implied gap. Paper.
PAPER: Prefer 09:00 KRX auction vs soft NXT (−3.15%) after Fri DeepSeek/foreign dump — not BN↔HL (SKHX venue gap ~1 bp tight this snap; SKHY ~2 bp). Secondary: ADR ~+41% rich to parity is multi-day research, not a clean same-session sniper. Seoul rule NO (Fri cash −2.21% fails ≤−8% leg). CSOPSKHYNIX2L is 2× HK ETF — not the stock. Paper only. No live.
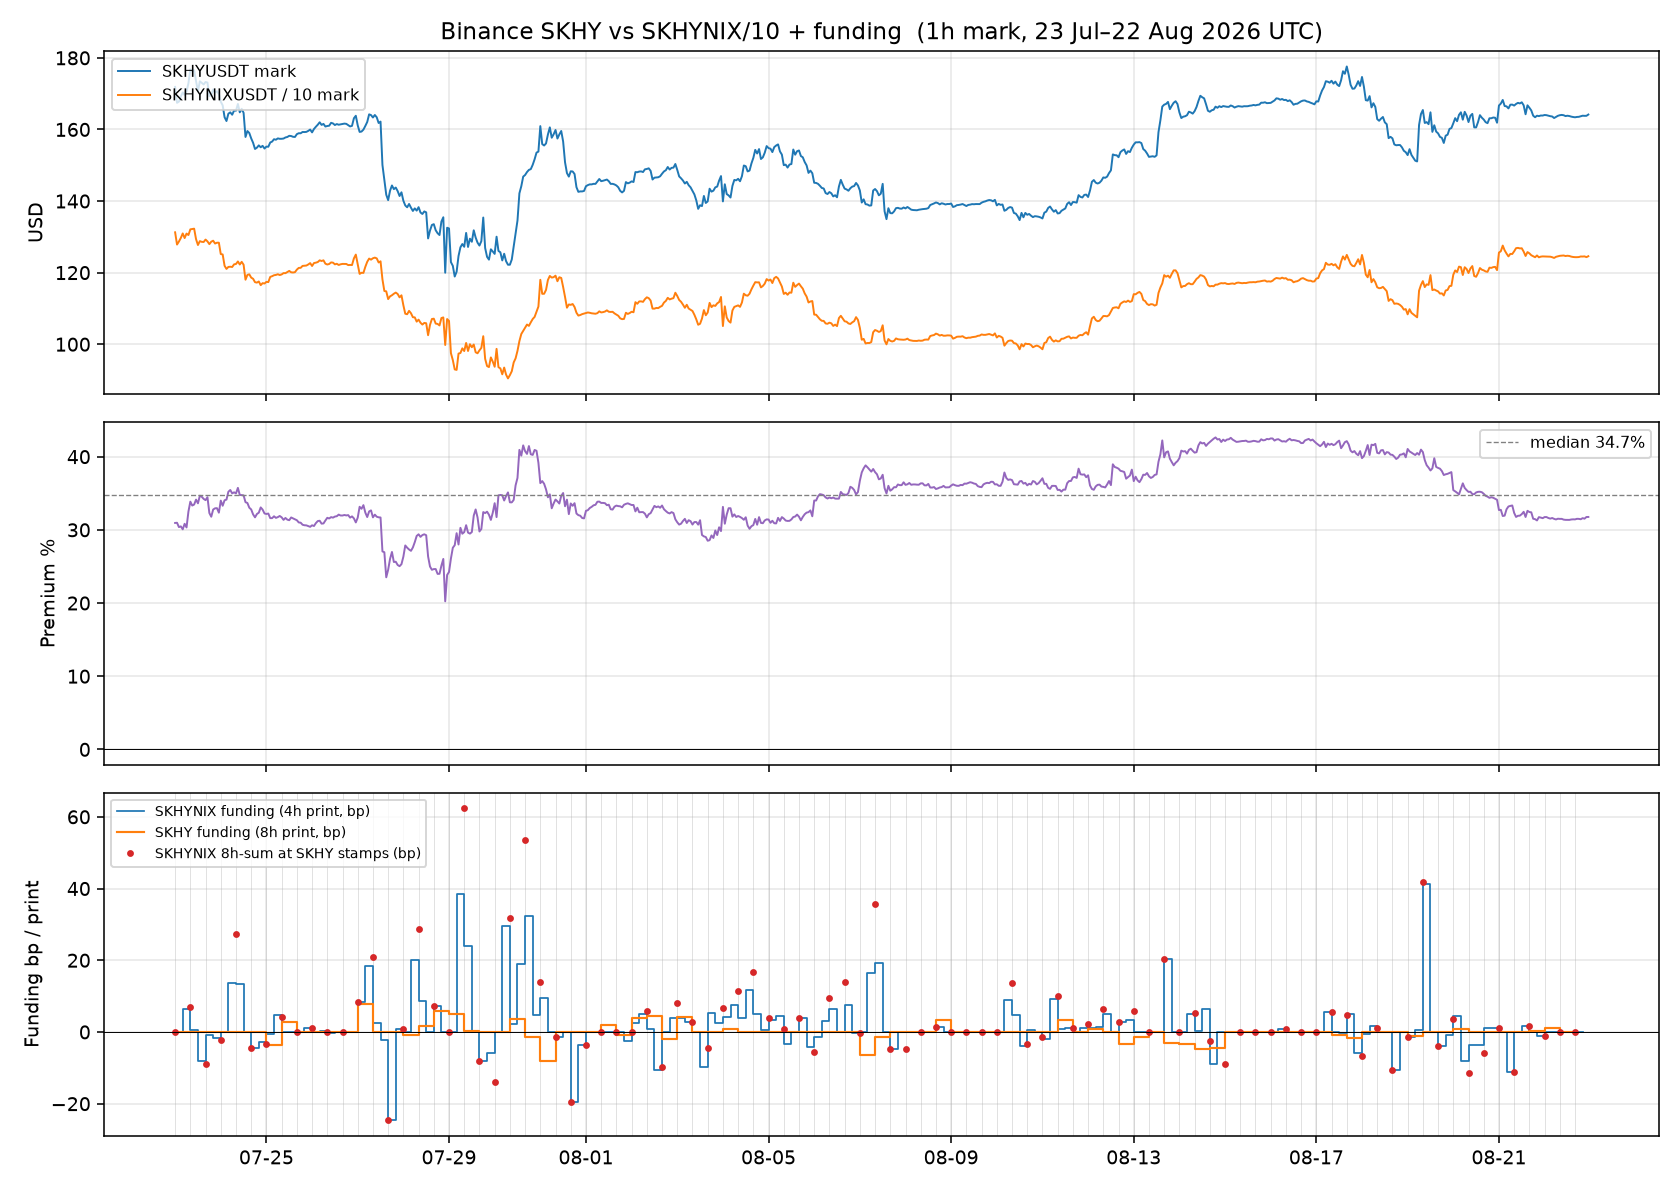
Charts refreshed 14 Sep 2026 08:09 HKT / 14 Sep 2026 09:09 KST (rolling 7d BN↔HL). SKHYNIX↔SKHX mark ~+4.3 bp · SKHY↔SKHY mark ~-2.6 bp · ADR/KRX prem ~+41.42% Research/paper only.
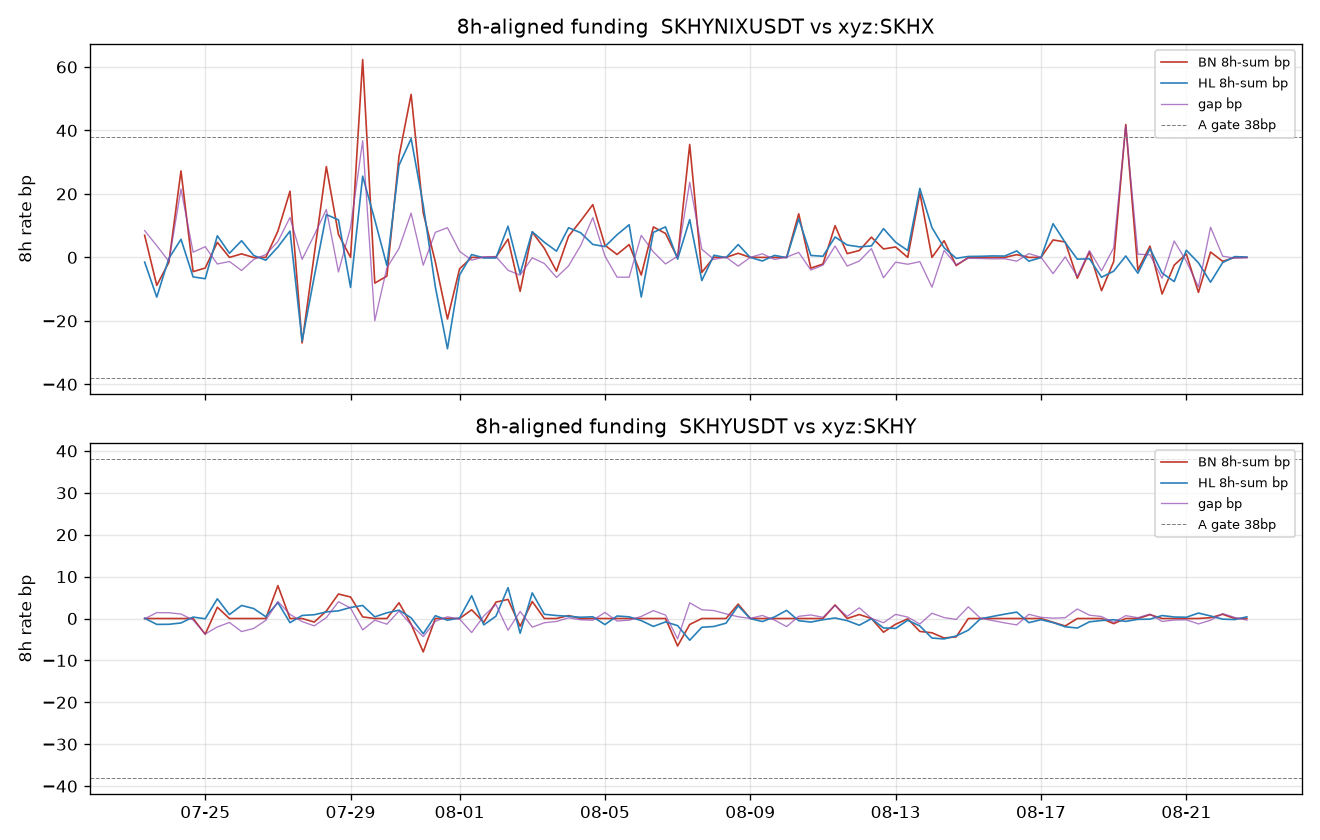
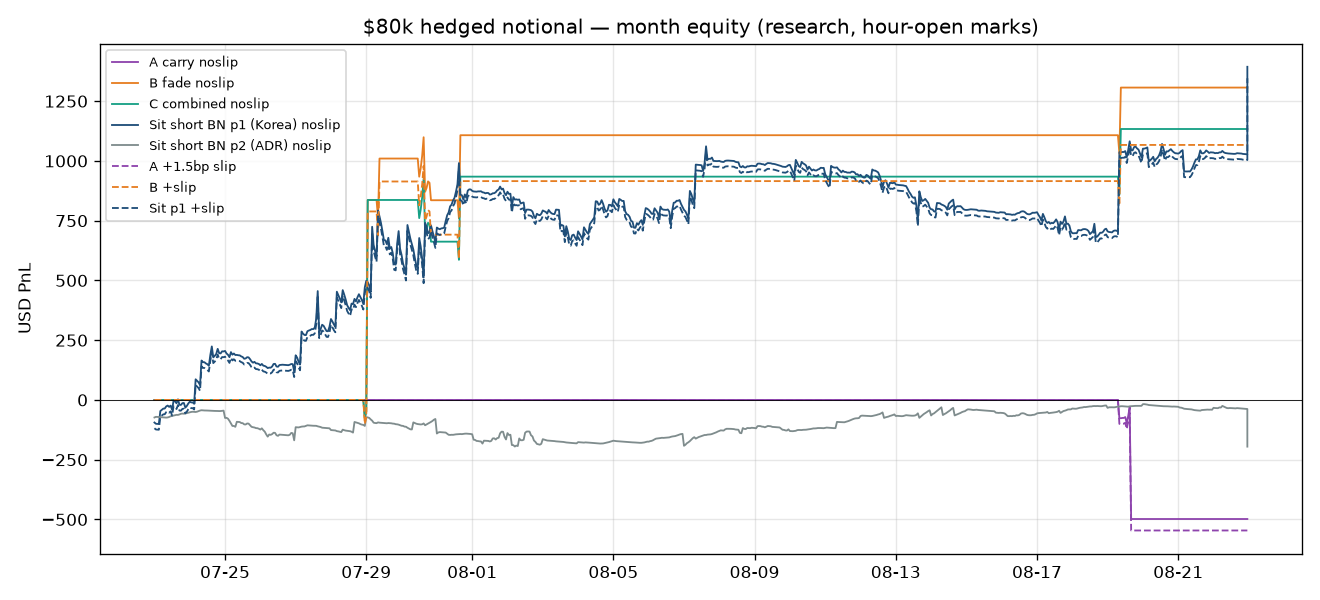
Bottom strip is ADR vs KRX cash premium (SKHY×10×USDKRW/000660−1), not the old backtest equity curve. Paper.
Live marks 2026-09-14 07:42 HKT / 2026-09-14 08:42 KST. SKHYNIX↔SKHX mark ~+1.0 bp (BN 1303.23 / HL 1303.1) · SKHY↔SKHY mark ~+1.6 bp (BN 181.89 / HL 181.86) · ADR/KRX prem Fri ~+41.2%. BN lastFR SKHYNIX +3.02 bp / SKHY 0; next BN 08:00 HKT. HL hourly funding SKHX +0.36 bp / SKHY +2.22 bp. Est. 8h long-BN/short-HL: SKHX ~−0.1 bp / SKHY ~+17.8 bp (HL path risk). Charts last refreshed 13 Sep (rolling 7d) — marks above are live. Research/paper only.
Seoul paper rule N/A (Fri cash −2.21%, not ≤−8%). NXT −3.15% not a Seoul-rule input. Excluded CSOPSKHYNIX2LUSDT. Paper only.
| Ticker | Follow | Note |
|---|---|---|
| AVGO | Y | Live. Post-Q3 beat + raised guidance; stock sold off. AJ memo + X teaser. No new overnight AJ idea. Body paywalled. |
| NIO | Y caution | China concentration. Unchanged. |
| EOS | Y avoid | Separate from EOSE. |
| NVDA | Y | Still live. Overlay: DeepSeek efficiency scare + Anthropic China-lab distillation politics + FOMC week. |
| MRVL | Y | Follow-up Y. Unchanged. |
| MU | Y | Cheapest PEG (22 Aug AJ). Overlay: Jukan MU HBM +60k→~100k YE (most aggressive of 3); Zephyr 12Hi→8Hi mix pushback; DeepSeek scare + Fri KR dump. |
| XPEV | Y | AJ $12.20 / IRON. Unchanged. |
| META | booked | Tactical; no new long. Meta Korea won-bond color (KED) — thematic only. |
| AMD | Y | Y confirmation: AJ buy flag $453 (2 Sep) → Fri $516 (+14%/9d). Leopold SA calls + #3 fabless ranking (Jukan). |
| ORCL | Y | NEW vs Y (AJ). Beat+guide + Post Q3 memo; HC models enter-vs-wait — still wait, don’t chase. Not a confirmed public long add. |
| PLTR / AAPL | N / event | PLTR expensive. AAPL: Duo hinge supply friction carry — not AJ idea. |
| EOSE | avoid | AJ red flags |
| TSLA | caution | AJ robotaxi race-to-bottom overlay; still caution not a long. |
| GM | color | Trump China-plants-in-US remarks (KED) — color for KR autos; not a long. |
| RIVN | N | Skip. |
| SPCX | watch | Unchanged. |
| BWET | color | Citrini ‘Dayum’ QT — Iran Conflict Beta sleeve; thematic only. |
2026-09-14 07:42 HKT / 2026-09-14 08:42 KST. US cash overnight; Fri CPI printed (+0.4%/3.4%; core +0.3%) into FOMC 15–16 Sep. AJ: ORCL NEW vs Y (memo/beat; entry HC-gated — wait). AMD confirmation only. Sep 13 Market Valuation still paywalled. No confirmed new public long add beyond ORCL wait sleeve. Do not invent targets. Paper.
KRX PREOPEN. Attractive list EMPTY besides Hynix desk. Fri close: KOSPI 6,909.91 (−1.76%); 000660 1,812,000 (−2.21%); 005930 259,500 (−3.53%). NXT: 000660 1,755,000 (−3.15%); 005930 254,000 (−2.12%). SKHY ADR Fri $190.07; prem ~+41.2% vs Fri parity. No overnight clean 000660 DART keep. data.krx missing. Fri DeepSeek HBM scare + foreign −₩2.29tn already printed.
DART leftover that can matter at open: Korea Advanced Materials 062970 Lucent LP add ₩14.7bn (mixed/3-8%/p≈30% — affiliate fund, weekend into Mon). Prior Fri session leftovers (Hanwha Aerospace / Samsung E&A / i-Scream) were same-day Fri windows — treat as stale unless tape still gaps.
No new Korea attractive idea beyond Hynix desk + 062970 leftover. No live trade recs. Paper.
2026-09-14 21:54 HKT / 2026-09-14 22:54 KST · Home unavailable. Sentiment mixed, medium. NEW since afternoon 14:09: TrendForce/Jukan anti-4Hi; SEMCO–QCOM organic bridge; TeraFab WFE orders; Zephyr China AI ~$35B raise.
Jukan links TrendForceInsights arguing 4-Hi HBM isn’t enough for datacenter needs; personal add: memory makers wouldn’t produce 4-Hi even if bandwidth were “enough.”
Reinforces afternoon anti-de-spec tape vs SemiAnalysis 4-hi thesis. Constructive for higher-stack / ASP mix (MU / 000660 / Samsung).
tweetZephyr: Zhipu/Moonshot/DeepSeek ~$35B in 4–5 months (~7× pre-May); path ~$60B by Jan’27 with IPOs. Capital + efficiency enough to stay competitive; expects testing/safety scrutiny, not a near-term hard training-compute cap; ~9mo convert-to-compute lag.
Constructive funding color for China AI names on the morning watch; mixed for “pacing kills China catch-up.” Not a KR cash sniper tonight.
tweetKorea Economic Daily via Jukan: TeraFab largely completed Q2 front-end tool orders with ASML, AMAT, Lam, TEL; 2H staging back-end/packaging. Pilot end-2027, ops 2028. Hanmi supplying packaging tools for system semis.
Constructive KR foundry-build / WFE / packaging-equip tape. Secondary to Hynix cash but real supply-chain color into US open.
tweetTheElec via Jukan: Samsung Electro-Mechanics + Qualcomm (and others) on organic-bridge AI multi-die 2.1D packaging — organic RDL bridge in FC-BGA as EMIB alternative. >1y validation; Samsung Foundry packaging path also in view.
Constructive SEMCO FC-BGA / advanced-packaging pivot after afternoon glass-substrate delay. Soft QCOM packaging optionality.
tweetJukan reposts Jeff Pu: shares TrendForce view that de-spec to 4-Hi is low-probability, vs SemiAnalysis-style worries that 4-Hi could match bandwidth with fewer dies / cut inference cost / stretch DRAM.
Soft pushback on 4-hi thesis — mixed stack-height tape. Evening TrendForce follow-up strengthens this side.
tweetJukan: Samsung Electro-Mechanics TGV/glass TSMC reliability eval delayed >1 mo; investment pace moderated toward FC-BGA + AI/auto MLCC. SK hynix extending multi-year demand forecasts. SOCAMM2 / DDR5 RDIMM PCB orders rising.
Mixed packaging: soft near-term glass; constructive 000660 prep + module PCB. Evening SEMCO–QCOM organic-bridge note is the FC-BGA follow-through.
tweetZephyr on Sam Altman pacing note: reads as 500k Vera Rubin training run next year rather than 1M in 2027; 15–25% of compute to monitoring/alignment.
Continues pace-frontier tape — soft for linear max-training GPU pull into 2027.
tweetJukan QT: Micron Taiwan’s Taoyuan plant union rejected NT$1m ‘appreciation bonus’ and threatened strike; wants 15% profit-sharing when profitable plus downturn safeguards.
Soft labor/ops overhang for MU Taiwan fabs — mixed headline risk inside still-constructive HBM cycle.
tweetJukan one-liner with chart: SoftBank −11% (Mon session tape).
Risk-off color for SoftBank / Vision Fund / AI-holdco complex; soft spillover watch for Japan risk assets.
tweetNikkei via Jukan: MLCC content/mix per AI server rising; AI MLCC demand at least through 2028; reviewing capacity beyond ¥80bn equip through FY Mar-2028.
Constructive MLCC / AI-server components tape.
tweetAJ: flagged AMD at $453 as buy on 2 Sep 2026; stock closed Fri 11 Sep at $516 (+14% ex-leverage) in 9 days — cited as HC trade example.
Bullish AMD confirmation of standing Y long — not a new ticker. Quiet on public X this evening.
tweetAsiae via Jukan: MU plans +60k wafers/mo HBM by YE (~100k total); vs Hynix ~200k and Samsung ~250k YE.
Constructive MU HBM share/mix (standing Y).
tweetMethod: api.fxtwitter.com profile statuses + status enrich (evening 9:30 HKT / US hours pass). Home unavailable. Cutoff: newer than 2026-09-14 14:09 HKT. Skipped culture-war / lifestyle (BowTiedBull) and AJ satire/Starship. Full machine JSON: x-feed.json.
Overall: mixed — evening constructive for higher-stack HBM + KR packaging/WFE (SEMCO organic bridge, TeraFab tools) and China AI funding path; afternoon SoftBank dump + MU Taiwan labor + Vera Rubin pacing soft still in the book. Selective AI/memory tape. Not a clean KR auction sniper from X alone.